Ownership shift
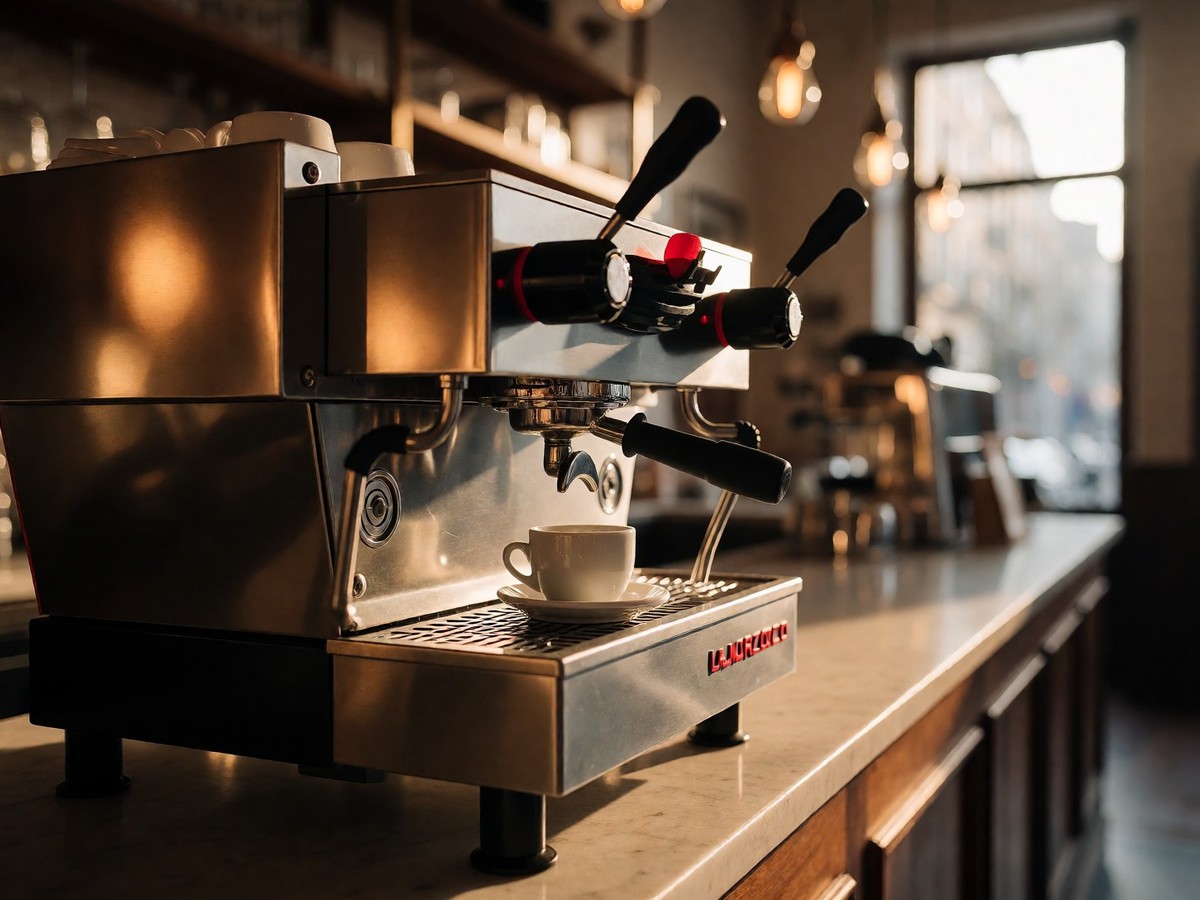
De’Longhi increased its controlling stake in its professional coffee division, which includes the brands La Marzocco and Eversys, to 88.02 percent after acquiring shares held by DLI Limited. This moves the ownership up from 61.56 percent. I find the €662.5 million (US$741 million) price for these shares logical given the division’s recent performance. The group funded the acquisition through a combination of existing cash reserves and debt facilities, which strengthens the position of De’Longhi in the global professional coffee equipment market. This division’s revenue reached €569 million (US$657 million) for the 12 months to 30 June 2026.
| Metric | Value |
|---|---|
| Enterprise Value | €2.36 billion (US$2.64 billion) |
| Equity Value | €2.5 billion (US$2.8 billion) |
| Minority Stake | 11.98% |
| Possible IPO Date | March 2028 |
The professional division’s enterprise value is €2.36 billion (US$2.64 billion) while the equity value is €2.5 billion (US$2.8 billion). I see the decision to simplify the ownership structure as a way to support the long-term growth strategy in coffee.
Financial growth
The division’s revenue grew 38 percent year-on-year for the 12 months ending 30 June 2026, following the December 2023 business combination of La Marzocco and Eversys that saw revenue increase by more than 50 percent. I view the 30.2 percent adjusted EBITDA margin, which reached €172 million (US$192 million), as the most impressive part of the division’s recent results. Fabio de’ Longhi, the De’Longhi Group CEO, says the investment "strengthened our market leadership in the professional coffee sector, creating an additional growth engine for the Group." This revenue of €569 million (US$657 million) is a massive jump compared to the previous 12-month period. The division’s adjusted EBITDA reached €172 million (US$192 million).
Minority shareholders will retain an 11.98 percent stake in the business, meaning they hold the ability to seek an initial public offering of the professional division from March 2028. The division’s revenue of €569 million (US$657 million) matches the 38 percent increase recorded over the previous year. Since the business combination was announced in December 2023, revenue has increased by more than 50 percent and adjusted EBITDA has doubled. I see the 30.2 percent margin on the €172 million (US$192 million) adjusted EBITDA as evidence of a healthy division. The group reported a positive net financial position of €687 million (US$769 million) as of 30 June 2026. The division also reached an equity value of €2.5 billion (US$2.8 billion).
Topics