Financial recovery and expansion
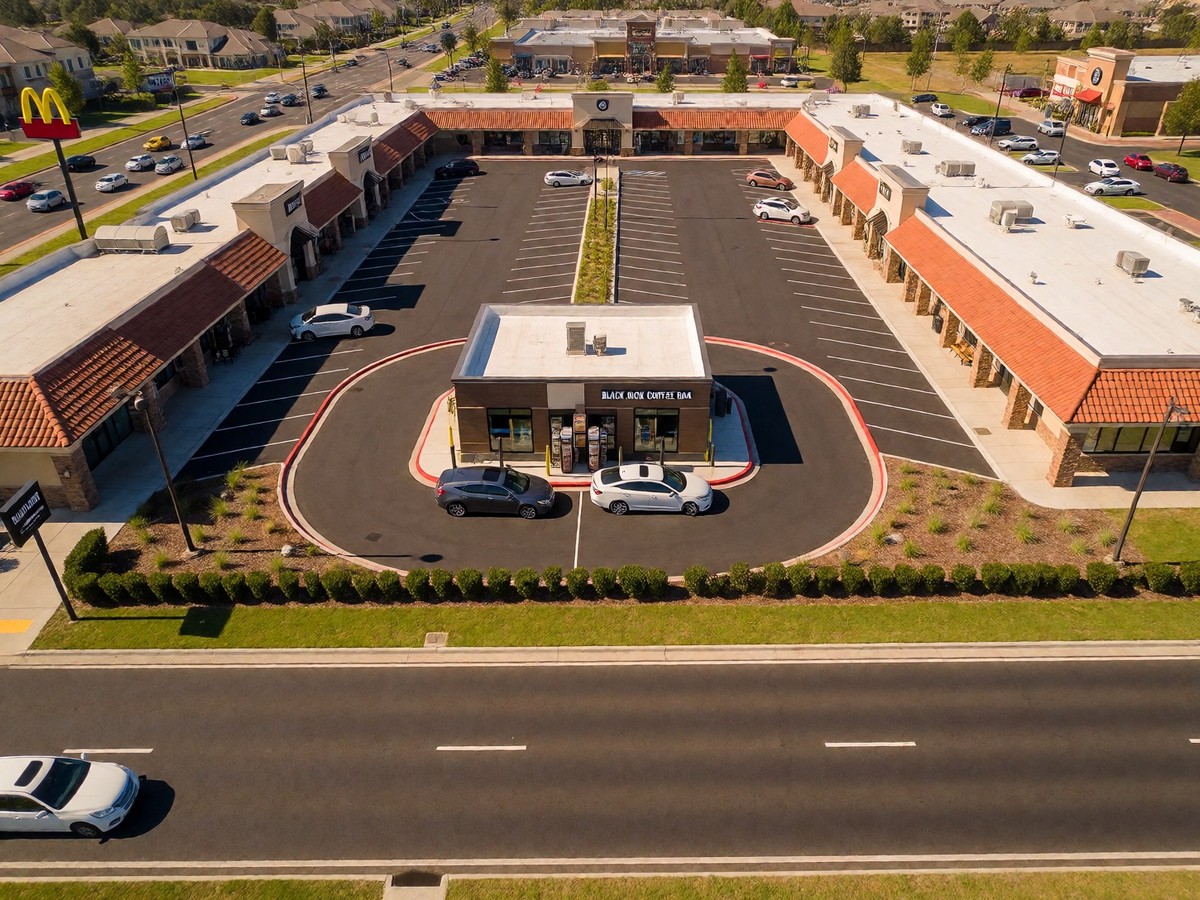
Black Rock Coffee Bar reported $66.8 million in revenue for the three months ended September 30, 2026, a 29.7 percent increase from the same period in 2025. The US drive-thru chain also achieved a net income of $2.7 million, which reverses the $16.2 million net loss the company reported during the third quarter of 2025. I see a massive swing in profitability as operating income climbed to $2.8 million from a $6.4 million operating loss reported a year earlier. Same-store sales grew 5.8 percent, marking the 15th consecutive quarter of positive comparable-store sales growth for the retailer. The company opened 11 new stores during the quarter to reach 211 locations across seven US states, and because it is ahead of its development schedule, it raised its full-year target for new store openings to 40 locations.
Operational momentum and debt
CEO Mark Davis says that menu innovation and expanded operating hours, alongside enhancements to the company’s loyalty programme, drive customer engagement and increase visitation throughout the day. Davis reports that "positive transaction growth and accelerating same-store sales underscore the momentum Black Rock Coffee Bar is building as it pursues further expansion across the US market." He says revenue increased 30 percent and adjusted EBITDA grew 22 percent year-over-year. Davis also notes that same-store sales reached 5.8 percent, which is 16.6 percent on a two-year basis, while positive transaction growth reinforced confidence in consumer demand. I find his optimism warranted as adjusted EBITDA grew 22.1 percent to $8.5 million.
| Metric | Q3 2026 Value |
|---|---|
| Revenue | $66.8 million |
| Net Income | $2.7 million |
| Adjusted EBITDA | $8.5 million |
| Total Debt | $38.1 million |
| Cash | $13.6 million |
I find the company’s debt load concerning, as the $38.1 million in total debt reported as of September 30, 2026, significantly exceeds the $13.6 million in cash and cash equivalents it holds. The company also reaffirmed its full-year 2026 financial guidance, forecasting revenue of $255 million to $257 million and adjusted EBITDA of $34 million to $35 million, with mid-single-digit same-store sales growth. As of the end of the third quarter, the company held $13.6 million in cash and cash equivalents.
Topics